Puppy Sphere Raises First Outside Capital After Bootstrapping to $14M Across 13 Studios
The experiential wellness brand co-founded by Francesca Albo and Lea Burbidge Izquierdo reached 13 North American studios and more than 450,000 customers before taking any outside investment.
- Cumulative revenue
- $14M+, reported, achieved before first outside capital
- Studio count
- 13 studios across North America
- Customers served
- 450,000+, reported
- Funding stage
- First outside capital; terms not disclosed
- Brand partners
- Amazon, Netflix, iHeart Radio, The New York Times, per the company
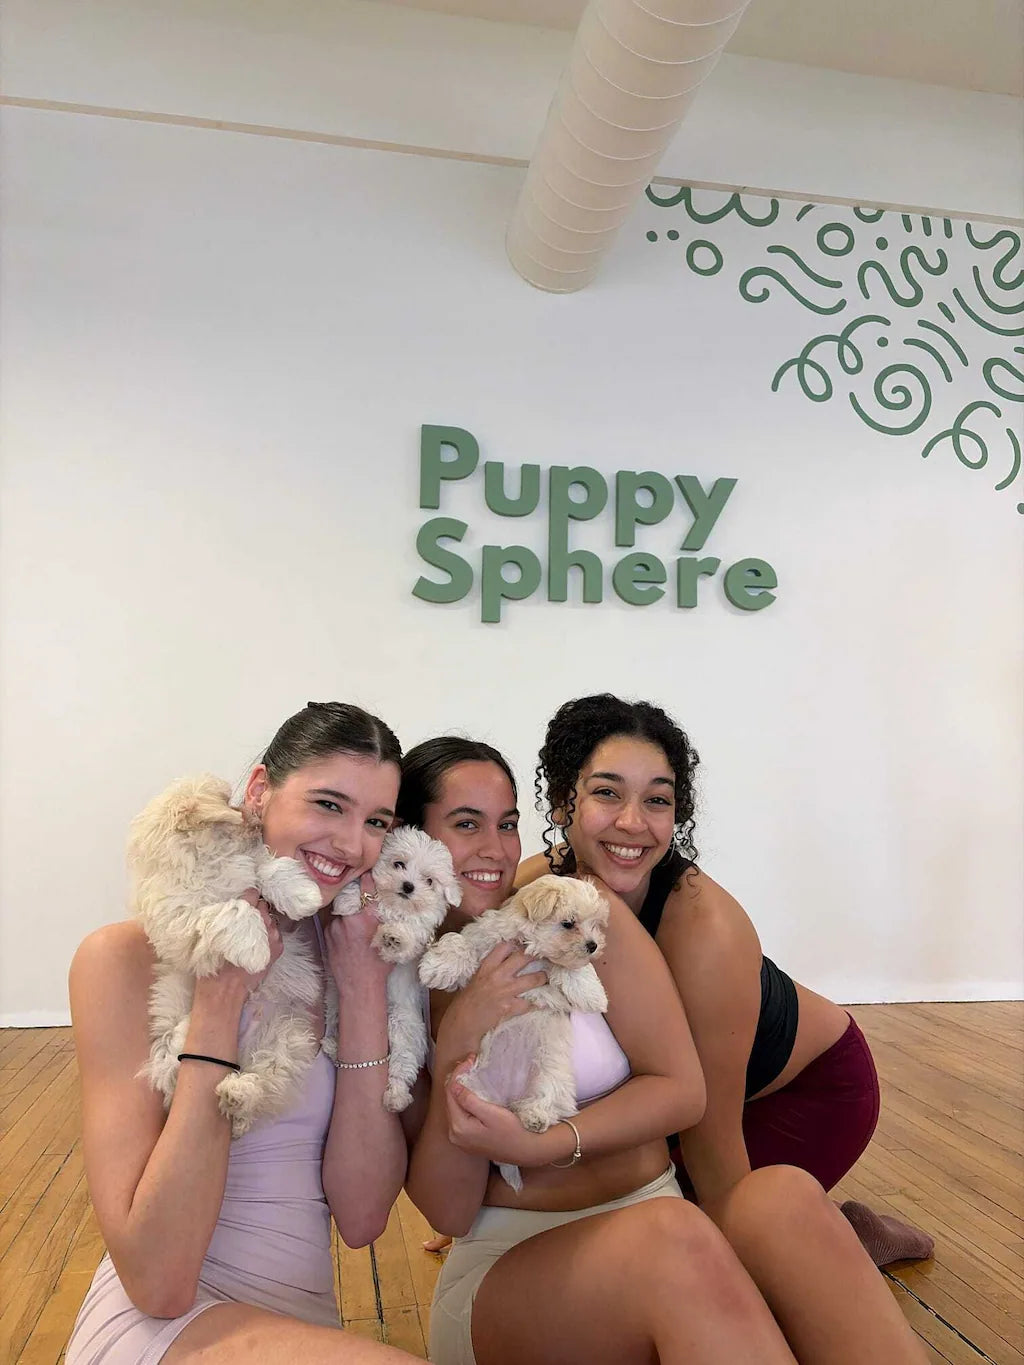
Puppy Sphere, which positions itself as North America's original puppy yoga company, has closed its first round of outside capital after scaling to 13 studios and more than $14 million in cumulative revenue entirely through bootstrapping. Terms were not disclosed.
The company was co-founded by Francesca Albo and Lea Burbidge Izquierdo, who trace its origins to their own experiences with stress and burnout during demanding corporate careers. Puppy Sphere now operates three class formats across cities including Chicago, New York, Washington D.C., California markets, Toronto, Mississauga, Montreal, Ottawa and Winnipeg, and has served more than 450,000 customers across those locations. Beyond consumer classes, the business has developed a corporate and events channel covering team-building programs, employee wellness, client appreciation and brand activations. Brand partners have included Amazon, Netflix, iHeart Radio and The New York Times, per the company.
The funding announcement marks a meaningful inflection point for a concept that sceptics might have dismissed as a novelty. Reaching 13 studio locations and a nine-figure cumulative customer count without institutional backing demonstrates that structured human-animal interaction commands durable repeat demand, not merely viral curiosity.
Why it matters
Puppy Sphere's milestone illustrates a pattern gaining traction across experiential wellness: founders who achieve genuine scale before seeking outside capital arrive at the negotiating table with far more leverage than those who raise early on a concept alone. The company's $14 million cumulative revenue figure, built without dilution, sets a credible floor on valuation conversations. The category itself sits at the intersection of boutique fitness and pet culture, two segments that have each attracted sustained investor attention. Puppy Sphere's dual revenue model, combining per-class consumer bookings with corporate programming, also reduces dependence on any single channel and gives it a margin profile more resilient than a single-format studio operator.
What to watch
The central open question is how the new capital is allocated between physical studio expansion and the corporate and events business. The latter carries substantially lower real estate overhead and can grow without the fixed costs tied to a brick-and-mortar footprint, making the strategic weighting of that investment a telling signal about where leadership believes the category's most scalable economics actually lie.
Featured on @cpglatest: see the post
Sources
Related coverage
Dan-O's Seasoning Secures $25 Million PE Investment from The Newcastle Network
The Louisville-based spice brand, now in more than 22,000 U.S. retail doors, will use the capital to develop new product formats and extend its retail and online reach, per The Newcastle Network's announcement.
Intake Breathing Raises $62 Million From Camino Partners to Enter Mass Retail
Camino Partners, founded by KIND Snacks' Daniel Lubetzky, backed the round as the magnetic nasal dilator brand prepares to move beyond its DTC and Amazon channels into mass retail, per Modern Retail.
Kalshi Closes $1 Billion Round at $40 Billion Valuation
CNBC reported that Kalshi's $1 billion raise co-led by Sequoia Capital and Wellington Management values the exchange nearly eight times higher than it was just one year ago.